What Employees Over 65 Cost a Small Group Plan in 2027
A 64-year-old costs 3 times a 21-year-old on most small group plans. See the 2027 math, the 20-employee Medicare rule, and the PEO catch.
Insights
Expert analysis on employee benefits, insurance strategy, compliance, and cost optimization for employers and brokers.
384 articles
A 64-year-old costs 3 times a 21-year-old on most small group plans. See the 2027 math, the 20-employee Medicare rule, and the PEO catch.
At 70 employees, our 2027 model across 48 states shows a captive's bad-luck year still saves money while level funded loses. Here is why.
Insurers filed a median 14% small group increase for 2027. See how that changes level funded vs fully insured odds for your group.
ACA penalties for employers explained: 2026 and 2027 4980H amounts, mid-market 95% cliff exposure figures, monthly accrual math, and answering Letter 226-J.
See how an embedded deductible works in a 2026 family health plan, how it differs from an aggregate deductible, and the IRS and ACA limits employers must meet.
Learn how COBRA insurance cost is calculated for employers. The 102% premium rule, 2025 average premiums, and how to explain the price to exiting employees.
The two December 2024 ACA laws let you stop mailing 1095-C forms, but a new six-year statute of limitations means employers should hold records longer, not shred them. Here is the playbook.
IRS Notice 2026-5 expands HSA eligibility for 2026. See which employees qualify through telehealth, direct primary care, and bronze plans, plus the 2026 limits and a pre open enrollment checklist.
An unaffordable QSEHRA reduces the premium tax credit while an affordable ICHRA removes it, and each is measured against a different benchmark silver plan.
See what a PEO and an ASO each hand your business: co-employment, self funding, ERISA fiduciary duty, and the CPEO wage base rule that decides when you can switch.
Learn how employers process a QMCSO or National Medical Support Notice, meet the 20 and 40 business day deadlines, enroll a child, and document payroll.
The 2026 commuter benefits limit is $340 monthly. Compare employer mandates in New York, New Jersey, DC, Seattle, Philadelphia, California, and Illinois.
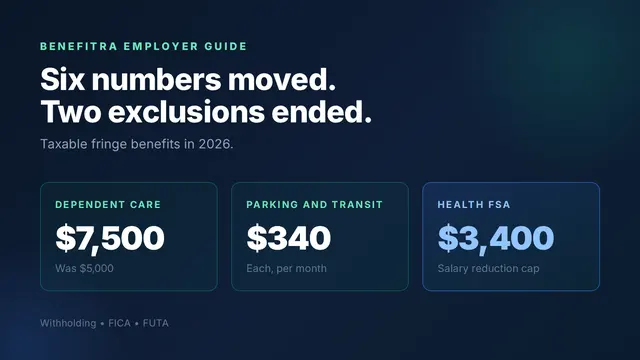
Taxable fringe benefits changed in 2026. Dependent care rose to $7,500, parking and transit sit at $340, and two exclusions ended for good.
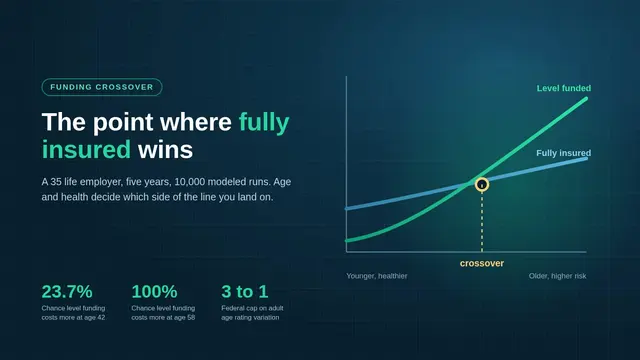
When fully insured is better than self funded depends on age, health, and group size. A 35 life model shows where level funding stops winning.
Level funded vs self funded is the wrong divide. Federal law calls both self insured, moving four federal filings and a $3.84 per covered life fee to you.
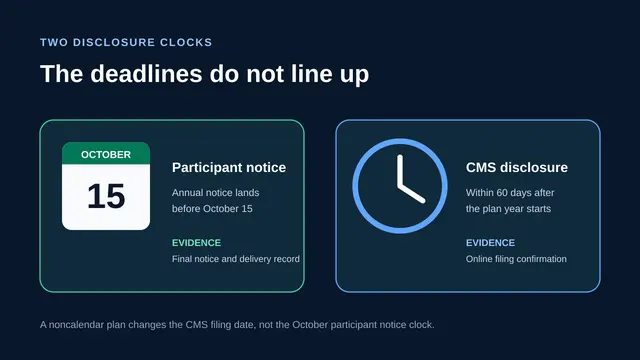
Use this 2026 creditable coverage notice guide to test Medicare Part D status, meet CMS deadlines, document notices, and prepare for 2027.
Direct primary care became HSA compatible in 2026 under Section 71308, capped at $150 a month. See the actuarial data and employer tax math behind it.
Dependent care FSA limits rise to $7,500 in 2026, the first increase in 40 years. See the employer FICA math and real childcare cost data behind the change.
Ground ambulance coverage can still expose employees to surprise bills. See the claims data and five plan terms employers should audit before renewal.
The 2027 ACA affordability percentage is 10.22%. See the federal poverty line cap, hourly payroll math, and contribution checks employers need for 2027.
Small employers can self-fund in most states, but stop-loss rules can change the economics. See the 2026 thresholds, exceptions, and quote checks.
Convert 2026 health cost growth into construction labor hours, crew weeks, and the bid revenue needed to fund a renewal.
Learn who handles the 2026 gag clause attestation for group health plans, what vendors can file, and what proof employers should keep before December 31.
Missed RxDC reporting or a carrier survey? Learn what employers should verify now, which files may be missing, and how to document next steps.
July 31 can trigger PCORI fee and Form 5500 action. Use this employer health plan checklist to split payment, filing, extension, and vendor tasks.
Employer health premiums rise in 2026 as inflation and utilization shift. KFF and Healthcare.gov guidance helps employers catch retention risk before renewal.
ICHRA affordability in 2026 can shift by county. Use IRS 9.96% limits and CMS silver rates to catch employer allowance gaps before renewal pricing starts.
2027 HSA limits rose again, but the real employer decision is how much HSA funding offsets deductibles employees face before care feels usable at renewal.
The 2026 ACA affordability percentage gives employers more room on employee-only premiums, but that compliance test does not measure what workers pay for family coverage. This article shows how to price the family premium gap before renewal.
The federal No Surprises Act guarantees 90 days of continued care for only five narrow categories, so most employees in routine therapy fall outside it. Here is the fix.
No articles match your search.